Captive Agency Growth: Which Bet to Make First in 2026
Craig and Jason are licensed P&C agency owners, co-authors of Million-Dollar Agency, creators of the trademarked Telefunnel, hosts of The Insurance Dudes podcast, and speakers.
Written and reviewed under our editorial process. Found an error? See our corrections policy.
A captive agency owner has three growth levers: keep the households you have, sell them more, then buy new ones. Most owners pull acquisition first and wonder why the math never works out. Sequence retention and cross-sell ahead of new-customer spend, and growth stops being a bet and starts being a system.
TL;DR
Growth is a sequence, not a choice among unrelated tactics. Retention keeps the households you already paid to acquire. Cross-sell grows each household without a single new lead. Acquisition is the last lever, not the first. Pull them in the wrong order and you fund churn with fresh lead spend. Sequence them correctly and every new customer you buy compounds instead of leaking out the back.
You have three ways to grow a captive agency, and only one of them costs new money every month. The mistake most owners make is pulling the most expensive lever first, because it feels like progress. You buy leads before you fix the front door, then watch the households you already paid for walk out while you raise the lead budget to replace them.
Key Takeaways on growth sequencing?
- Retention is the cheapest growth lever, and a five-point drop can erase roughly a third of a household's lifetime value.
- Cross-sell grows revenue and retention together because bundled households churn far less than monoline ones.
- Acquisition only compounds when your retention and cross-sell engines already hold the households you buy.
- The sequencing rule is simple: keep what you have, grow what you have, then buy more.
"Growth is a math problem before it is a marketing problem. If your retention leaks faster than your acquisition fills, no lead vendor on earth can save you." - Sheppard Bowen, Co-Founder of EVER.PARTY and Former Insurance Agency Owner
Why is retention the first growth lever for a captive agency?
Retention is the only growth lever that costs nothing new and pays you for years. A captive owner fighting rate hikes already feels this in the gut, because every renewal that walks is a household you already paid a cost per sale to land. The math is not soft. Bain's research on P&C insurance customer loyalty found that a five-point retention lift can raise profits by anywhere from twenty-five to nearly one hundred percent depending on the book, because loyal households renew, bundle, and refer instead of shipping.
The retention math turns punishing fast when it goes the wrong way. Average renewals equal retention divided by one minus retention. At ninety percent you get nine renewals on average. At eighty-five percent you get five and a half. A five-point slip there cuts lifetime value by roughly thirty-seven percent, a number straight out of Bain's loyalty economics brief.
What does it cost to replace a household versus keep one?
Here is the sequence in dollars. If your stable cost per sale sits around one hundred fifty dollars, every household that leaves means you spend another hundred fifty just to stand still. Acquisition benchmarks compiled in the Reagan Consulting Best Practices Study consistently show that high-performing agencies run lower cost per sale by holding retention above ninety percent and cross-selling before they spend on new growth.
Retention processes are almost pure profit because the sale is already done. A courtesy call before the carrier mails a rate increase, a policy review that catches a life event, and a save script on a cancellation call all cost labor, not lead spend. That is why they come first.
Why does cross-sell come second, not acquisition?
Cross-sell grows the household you already have, which means the cost of that growth is a conversation, not a lead. A monoline household is a leak risk sized to one policy. A household with auto plus home plus umbrella plus a term life policy is a relationship sized to weather a rate increase, because switching all of it is a project most customers will not start.
Industry research on the life side reinforces the leverage. LIMRA's work on the benefits of cross-selling life insurance shows that a household with multiple products is demonstrably stickier and more valuable than a single-policy customer. For a captive owner under a life and financial services quota, cross-sell is the rare move where the corporate mandate and your own retention math point the same direction.
How do you find the cross-sell gap inside your existing book?
Pull your book and sort by policy count. The single-policy households are your cross-sell inventory, already sold on you, already paying you, just under-covered. A policy review with a shared screen that shows the gaps is the cheapest new revenue you will ever produce, and it never touches the lead budget.
Why is acquisition the last lever, not the first?
Acquisition is the only lever that consumes new dollars every single month, so it is the one you fund after the first two hold. Owners reverse the order because acquisition is visible. You can see the lead invoice and count the new policies. Retention and cross-sell are quiet, so they get skipped for the shiny number.
The problem is that buying customers into a leaking bucket is not growth, it is churn with extra steps. Your cost per sale stays high because you are paying twice, once to land a household and once to replace the one that left.
The distribution channel itself is not the issue. The Federal Insurance Office's annual report documents how essential agent-led distribution remains to the U.S. market, so the model is sound. The sequence is what breaks most owners.
How do you know your acquisition spend is ready to scale?
When your retention sits at or above ninety percent and your cross-sell runs as a scheduled process, then acquisition spend compounds. Before that, every new lead is partly funding a leak. The sequencing rule gives you the test: hold what you have, grow what you have, then buy more. Most owners know retention matters. They just never put a number to the leak before they raised the lead budget.
How do I sequence these three levers this quarter?
Start with retention this week. Pull your last quarter of non-renewals and sort the reasons. A courtesy-before-renewal call and a cancellation save script are the first two fixes, and both are pure labor, not lead spend.
Second, run a policy-count sort on your book and book policy reviews for every monoline household. That cross-sell motion feeds retention and revenue at once. Third, only after those two are running do you open the acquisition faucet, and when you do, you know your cost per sale against a book that is no longer leaking.
For a fuller playbook on the growth plays themselves, see Victor Figueroa's decade-tested framework in our agency playbook conversation. The tactics he ran map to this exact sequence: niche depth and claims service for retention, persistent follow-up for cross-sell, then brand for acquisition last.
If you have not yet put your cost per sale and lifetime value into a spreadsheet, start with our growth math primer on cost per sale versus lifetime value. And when you are ready to buy leads with the sequence in place, run the lead economics from our captive agency lead economics guide so the spend compounds instead of leaking.
What is the bottom line on sequencing captive agency growth?
Growth is an order of operations, and the order flips how every dollar behaves. Keep the households you have, grow the ones you have, and only then spend to buy new ones. Pull retention and cross-sell first and your acquisition budget finally starts to compound instead of funding churn.
Sources cited in this analysis?
Listen to The Insurance Dudes Podcast
Get more strategies like this on our podcast. Available on all platforms.
Related Episodes
Three Swings: Turn One Policy Into a Whole Household
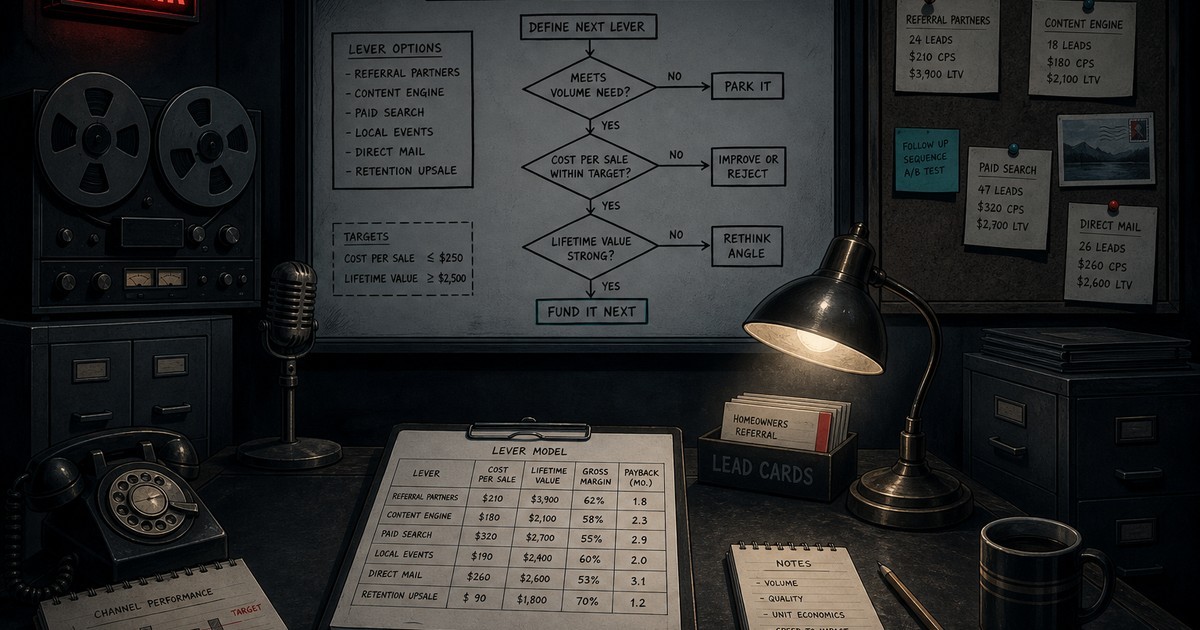
How to Pick an Insurance Agency Growth Strategy That Works
The Agency Growth Math: Cost Per Sale vs. Lifetime Value
Captive Agency Growth Architecture: The Systems That Scale
Why Your Lead Data Never Pays Off (And the Tier Fix)