What Makes an Insurance Agency Valuable to a Buyer
Craig and Jason are licensed P&C agency owners, co-authors of Million-Dollar Agency, creators of the trademarked Telefunnel, hosts of The Insurance Dudes podcast, and speakers.
Written and reviewed under our editorial process. Found an error? See our corrections policy.
An insurance agency buys on recurring revenue, clean books, and a retention rate that proves the book survives the owner. Buyers do not pay for your effort. They pay for a repeatable business that runs without you. Build retention, role separation, and a documented process first, and the multiple follows.
TL;DR
Buyers do not pay for your effort or your years in the seat. They pay for a book of recurring revenue that keeps renewing after you leave the building. Build retention, clean financials, and a team that runs without you, and the valuation multiple takes care of itself.
An agency is worth what a buyer will pay for its future renewals, not what you spent to build it. The dated rule of thumb that a book sells for 1.5 times annual revenue is, as Reagan Consulting puts it, dangerously inaccurate. Real value comes from three things a buyer can verify from outside the shop.
Key Takeaways on agency valuation?
- Buyers pay for recurring revenue that survives the owner, not for the owner's effort or tenure.
- A retention rate near or above 90 percent protects the valuation while a book that leaks renewals forces earnouts and discounts.
- Clean, documented financials turn a number on a napkin into a real multiple.
- A team that runs on process, not on you, is the difference between a sellable asset and a job.
- Private equity capital now backs roughly three in four agency acquisitions, so the buyer pool is real and growing.
What makes an insurance agency worth money to a buyer?
A buyer values one thing above everything else: the renewals. An insurance book throws off commission every six or twelve months as long as the policies stay on the books, so a buyer is really purchasing a stream of future revenue. The owner who understands this builds the agency backward from it instead of chasing premium for its own sake.
The math is straightforward. When a buyer prices your agency, they apply a multiple to your earnings, but the multiple itself is set by how defensible those earnings are. Reagan Consulting, the valuation firm that indexes broker transactions each year, scores value against its Best Practices Study and a proprietary value index rather than against a flat revenue multiple. That is because two agencies with the same revenue can be worth a factor apart if one runs on a clean, transferable system and the other runs on the owner.
Recurring revenue is the floor. Clean books raise the ceiling. A renewal stream the owner personally holds together does not transfer, so a smart buyer discounts it. The agencies that command premium prices are the ones where the renewals renew themselves through documented process and a real team.
Why does retention decide the multiple?
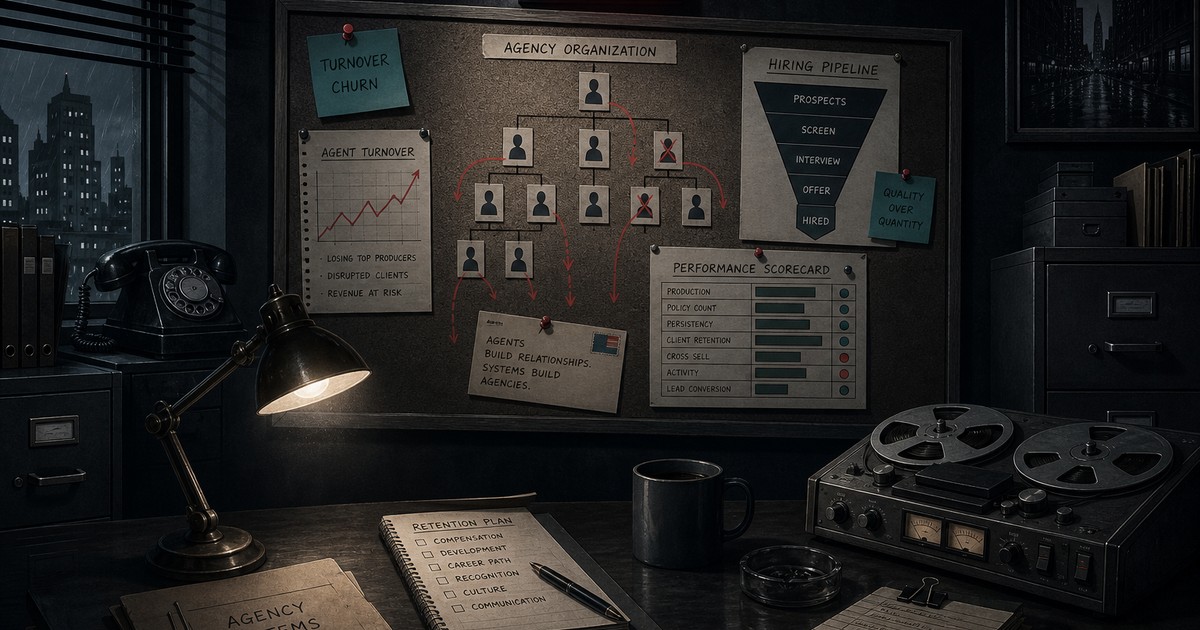
Retention is the single largest lever on value because it compounds. A five point drop in retention does not cost you five percent of the book. It costs you a growing share of lifetime value every renewal cycle, and a buyer prices that erosion in before they make an offer.
This is why the best agencies hold retention well above ninety percent while weaker books drift into the low eighties. That gap shows up directly in the sale price. The same retention math that rescues a new producer's first year is what a buyer prices when they open your book.
Here is the uncomfortable truth for the owner who built everything herself. If your clients stay because they like you personally, the buyer cannot buy that relationship. They can only buy the process that survives it. The agencies that sell well have moved retention out of the owner's head and into a system of pre-renewal calls, policy reviews, and cancellation saves that any trained staff member can run.
A buyer reads retention as a proxy for transferability. High retention with a documented retention engine means the buyer keeps the revenue. High retention that depends on a single relationship means the revenue walks when you do, so the buyer either walks or ties most of the price to an earnout.
How do clean books raise the price?
Clean books are the difference between a negotiation and a fight. A buyer cannot finance an acquisition on a spreadsheet full of personal expenses mixed into the business, so the first thing due diligence does is rebuild your numbers. If they come out lower than your story, the deal stalls or the price drops.
The agencies that close at premium multiples run their financials like a business from day one. Automated commission tracking, separated business and personal accounts, and a chart of accounts a third party can actually read. It is unglamorous work that feels like overhead until the day it becomes the reason a buyer trusts your number.
Reagan Consulting explicitly warns against valuing an agency that way. It hides the drivers that actually move price, the retention rate, the line of business mix, and the quality of the financial record. Clean books expose those drivers. Messy books hide them, and a buyer discounts what they cannot see.
What does a buyer actually pay for right now?
The buyer pool is real and it is consolidating. Risk and Insurance reported 520 agency transactions through the first three quarters of 2025, and private equity backed or hybrid buyers drove 73 percent of them. That concentration shifted the market hard toward institutional capital, a trend Risk and Insurance tracked into 2026 even as total deal volume eased to a decade low.
That concentration matters for you as a seller. Private equity buyers apply a financial lens, not a relationship lens. They model your renewal stream, your retention, and your operating leverage, then price to a return. The more your agency looks like a transferable business, the higher the multiple they will pay because they can drop it into their platform without you.
"Too often independent agencies seek to assess their value using dated standards such as the old norm of 1.5 times annual revenue. These standards never tell the whole story and may be dangerously inaccurate." - Reagan Consulting, Insurance Brokerage Valuation and Perpetuation
The Federal Insurance Office tracks this consolidation as part of its annual review of the insurance industry, noting the steady flow of capital into distribution and the intermediaries that own client relationships. A market with active, well-capitalized buyers is good for owners who built a clean asset and punishing for those who did not. You cannot control the buyer pool, but you control how sellable your agency is when they call.
How do I build the agency before I ever want to sell?
Build it as if the buyer is already in due diligence. That means three things today, not someday. First, get your retention into a documented process of pre-renewal calls, policy reviews, and cancellation saves so the book renews on system, not on personality. Second, make your financials clean enough that a stranger can read them. Third, remove yourself as the bottleneck so the business runs without your hands on every file.
This is exactly the operating system the owners with the best numbers already run. The agencies measured by Reagan Consulting vary in revenue but share a shape, a transferable process, a defined role for every person, and a retention engine that compounds. That is the same discipline behind the lead economics and cost per sale math that separate a scalable book from a stalled one. The owner who builds that shape gets a higher multiple whether they sell next year or in ten years.
The same discipline that makes an agency sellable is the discipline that makes it a better business to own today. Recurring revenue you trust, a team that runs without you, and financials you can read pay off whether you sell or hold. It is the same filter behind picking a growth strategy that scales.
What is the bottom line on building a sellable agency?
Your agency is worth what a buyer pays for its future renewals. That number is set by three things, retention, clean books, and a team that runs on process instead of on you. Stop measuring yourself by premium written and start building the three assets a buyer can actually verify. The multiple is not a mystery. It is a reward for building a business that does not need you.
Steps to take this week: run your twelve month retention number and find where renewals leak. Ask a trusted accountant whether a stranger could read your financials in an afternoon. Then write down the three tasks only you do today and start handing one of them to someone else. Build for the buyer and you build a better agency for yourself on the way.
Sources cited in this analysis?
- Reagan Consulting - Insurance Brokerage Valuation and Perpetuation (2026)
- Risk and Insurance - Agency M&A Activity Slows as Private Equity Tightens Grip on Market (October 2025)
- Risk and Insurance - Insurance Distribution M&A Hits Decade Low (April 2026)
- U.S. Department of the Treasury - Federal Insurance Office Reports and Notices
Listen to The Insurance Dudes Podcast
Get more strategies like this on our podcast. Available on all platforms.
Related Episodes
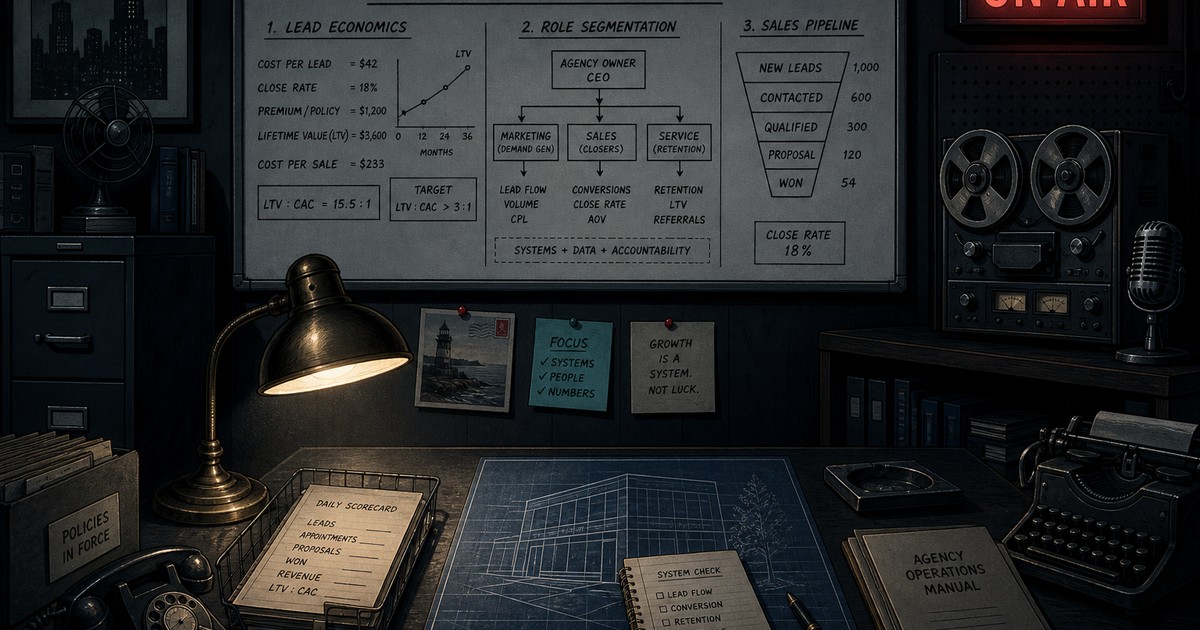
How to Grow an Insurance Agency in 2026: The System
Captive Agency Growth: Which Bet to Make First in 2026
Captive Agency Growth: Lead Flow, Role Math, and Retention
Eric Spring on What Satisfaction Scores Measure (Part 1)
Eric Spring on Turning Satisfied Clients Into Loyal (Part 2)